Because your home serves as your sanctuary, protecting it against the unexpected is not just a financial decision, but an act of care for yourself and the people you love. While the world of insurance policies can sometimes feel cold and complex, understanding the basics is the first step toward true peace of mind.
Homeowners insurance serves as a critical safety net, designed to help you repair or replace your home and belongings if they are damaged by events beyond your control.
Whether you are a first-time buyer stepping across the threshold of a new property or a long-time resident looking to update your coverage, navigating these waters does not have to be overwhelming.
By breaking down how these policies work, what they cover, and how to calculate what you truly need, you can ensure that your haven remains safe and secure, no matter what life brings your way.
- post content
- How Home Insurance Works
- What Home Insurance Covers
- Additional Riders to Consider
- How Much Home Insurance Do You Need?
- Securing Your Peace of Mind
- view table:content summary
- view notes:collective tips
- view ideas:latest remodeling analysis
- view article (new win):Reduce Home’s Risk Of Water Damage
How Home Insurance Works
At its heart, a home insurance policy is a contract between you and an insurance company. You agree to pay a set amount of money, known as a premium, and in return, the insurer agrees to pay for losses outlined in your policy.
Think of your premium as a subscription to security; it is typically paid monthly or annually to keep your policy active. The cost of this premium is determined by various risk factors, including the age of your home, the materials used to build it, your local crime rates, and even your credit score.
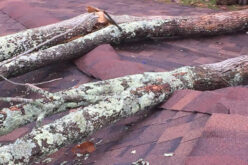
When a mishap occurs—such as a tree falling on your roof during a storm—you file a claim with your provider. This is where the deductible comes into play. The deductible is the amount of money you are responsible for paying out of pocket before your insurance coverage kicks in.
For example, if you have a $1,000 deductible and sustain $5,000 in damages, you will pay the first $1,000, and your insurer will cover the remaining $4,000. Choosing a higher deductible often lowers your monthly premium, but it is important to ensure you have that amount set aside in savings just in case.
Every policy also has a coverage limit, which is the maximum amount the insurance company will pay for a covered claim. It is crucial to set these limits high enough to cover the cost of rebuilding your home and replacing your possessions.
If your limits are too low, you could find yourself underinsured, meaning you would have to pay the difference out of your own pocket.
Understanding these three pillars—premiums, deductibles, and limits—creates the foundation for making informed choices about your protection.
supporting viewpoint
Protect Your Family from a House Fire: Essential Safety Tips Every Homeowner Needs to Know
When it comes to the safety and well-being of our loved ones, protecting our family from potential hazards is of paramount importance. One such threat that requires careful consideration is the risk of a house fire.


What Home Insurance Covers
A standard homeowners insurance policy is actually a package of several different types of coverage, each designed to protect a specific aspect of your life. The most prominent component is dwelling coverage.
This pays to repair or rebuild the physical structure of your house if it is damaged by a covered peril. This includes the roof, walls, floors, built-in appliances, and attached structures like a garage or porch.
If a kitchen fire destroys your cabinets or a windstorm tears off your shingles, dwelling coverage is what helps you restore your home to its former glory.
Beyond the physical structure, your policy also includes personal property coverage. This protects the items inside your home—your furniture, clothing, electronics, and other personal belongings.
If your home is burgled or your possessions are destroyed in a fire, this coverage helps you replace them. It is important to note that this protection often extends beyond the walls of your home; many policies cover your belongings even when you are traveling or if they are stolen from your car.
Two other vital components are liability protection and additional living expenses (ALE). Liability coverage steps in if someone who does not live with you is injured on your property, or if you accidentally cause damage to someone else’s property.
For instance, if a guest slips on an icy walkway or your dog accidentally bites a neighbor, liability coverage can help pay for legal fees and medical bills.
Meanwhile, ALE provides a financial cushion if your home becomes uninhabitable due to a covered event. It pays for hotel bills, restaurant meals, and other temporary living costs while your home is being repaired, ensuring your standard of living is maintained even during difficult times.
Additional Riders to Consider
While standard policies are robust, they often have specific exclusions that can leave homeowners vulnerable to nature’s more extreme temperaments. This is where riders, or endorsements, become essential tools for customizing your protection.
One of the most significant gaps in a standard policy is flood damage. Water damage from above, such as a burst pipe or rain entering through a damaged roof, is usually covered. However, water rising from the ground—like an overflowing river or storm surge—is almost always excluded.
If you live in an area prone to heavy rains or near a body of water, purchasing a separate flood insurance policy is a necessary step to safeguard your foundation and lower levels.
Similarly, earth movement is generally not covered under standard agreements. For those living in regions with seismic activity, an earthquake endorsement is a wise addition. This covers damages caused by earthquakes, including cracks in the foundation or structural collapse.
It is worth noting that these policies often have higher deductibles than standard home insurance, but the protection they offer against catastrophic loss is invaluable for those in high-risk zones.
You should also consider the limitations on specific categories of personal property. Standard policies often set dollar limits on high-value items such as jewelry, artwork, furs, or collectibles.
For example, your policy might cover personal property up to $100,000, but limit coverage for jewelry theft to just $1,500. If you own an engagement ring or a valuable painting, you may need a scheduled personal property rider.
This ensures these specific items are covered for their full appraised value, ensuring that your most treasured heirlooms are financially protected.
here’s another viewpoint

A Complete Guide to Protecting Your Assets and Valuables at Home
We often think of our homes as our personal sanctuaries—places where we can unwind, feel safe, and be our truest selves. But within these comforting walls, many of us store items that hold immense significance.
How Much Home Insurance Do You Need?
Determining the right amount of coverage requires a careful assessment of your property and lifestyle. A common misconception is that you should insure your home for its market value—what you could sell it for today.
However, you actually need to insure it for its replacement cost. This is the amount it would take to rebuild your home from the ground up at current construction prices.
Building materials and labor costs fluctuate, and they are often higher than the real estate market value implies. Speaking with a local builder or using an online calculator provided by insurers can help you estimate this figure accurately.
When it comes to personal property, the best approach is to conduct a home inventory. Go room by room and make a list of your possessions, estimating what it would cost to buy them new today.
Many homeowners are surprised by the total value of their clothes, kitchenware, media collections, and furniture when added together. This inventory not only helps you set the right coverage limit but also serves as vital documentation should you ever need to file a claim.
Finally, consider your liability coverage carefully. The standard coverage usually starts at $100,000, but in an increasingly litigious society, this may not be enough to protect your financial future.
Financial advisors often recommend purchasing enough liability insurance to cover your total net worth. If your assets exceed the limits offered by your home insurance policy, you might consider an umbrella policy, which provides an extra layer of liability protection across both your home and auto policies.
other related analysis of interest: (new win)
From Deck to Dream Room: A Conversion Guide
Navigating Home Emergencies: A Comprehensive Guide to Urgent Repairs
Securing Your Peace of Mind
Home insurance is more than a financial requirement; it is a promise to yourself that your sanctuary will endure. By understanding the mechanics of your policy, ensuring you are covered against specific risks like floods or earthquakes, and accurately calculating the value of your home and possessions, you are building a fortress of security around the life you have created.
Take the time to review your needs, speak with a professional, and ensure that your coverage reflects the love and effort you have poured into your home. When you are properly protected, you can rest easy, knowing that no matter what happens, you have a plan to rebuild and recover.
| Topic | Description | Details |
|---|---|---|
| Introduction | Overview of the importance of home insurance. | Your home is both a significant financial investment and a personal sanctuary. Protecting it is essential for financial and emotional security. |
| How Home Insurance Works | Explanation of premiums, deductibles, and coverage limits. | Premiums are regular payments for your policy, deductibles are out-of-pocket costs before coverage begins, and coverage limits define the maximum payout from the insurer. |
| What Home Insurance Covers | Breakdown of key coverage areas. | Includes dwelling coverage for structural damage, personal property protection for belongings, liability coverage for injuries or damages, and additional living expenses for temporary housing costs. |
| Additional Riders | Customizing policies for specific risks. | Flood and earthquake endorsements provide additional protection. Scheduled personal property riders cover high-value items like jewelry or artwork with higher coverage limits. |
| Determining Coverage Needs | Guidance on calculating appropriate coverage amounts. | Insure for replacement costs rather than market value. Conduct a home inventory and ensure liability coverage aligns with your net worth for comprehensive protection. |
| Securing Your Peace of Mind | Final thoughts on the value of proper coverage. | Home insurance safeguards your sanctuary and provides a foundation for rebuilding and recovery, offering both security and peace of mind. |

Find Handyman Services (opens new win) Handyman Carpentry Electrical Plumbing top-rated, pre-screened local contractors FREE: download contractor selection enter zip code – powered by HomeAdvisor ™


Image credit: home insurance guide by envato.com
end of post … please share it!
| more photo remodeling |
Jump Over to Our Photo Analysis Center for Ideas on
"Renovating Home"
|__________________________________________________________|
home remodeling surprise
find out where it might go - new win


Helpful article? Leave us a quick comment below.
And please share this article within your social networks.